

Weighing the markets – Counterpoint September 2026
8 mins to read this article
Daniele Antonucci
Daniele Antonucci is a managing director, co-head of investment and chief investment officer at Quintet Private Bank. Based in Luxembourg, he jointly chairs the investment committee, owning decision-making and performance outcomes. As head of research, Daniele oversees the investment strategy feeding into portfolios and the teams of specialists across asset classes and solutions, ranging from macro, fixed income and equities to funds, alternatives, and structured products and derivatives. He leads the network of chief strategists, communicating the house view on the economy and markets to financial advisors, clients and the media.
Prior to joining Quintet in 2020 as chief economist and macro strategist, Daniele served as chief euro area economist at Morgan Stanley in London. He completed the High Performance Leadership Programme at Saïd Business School, University of Oxford, holds a master’s degree in economics from Duke University and graduated from the Sapienza University of Rome. Featured in The Economist and Financial Times and often quoted in the generalist press, he’s a published author in finance and economics journals and investment magazines, a frequent speaker on CNBC and Bloomberg TV, and an ECB Shadow Council member.

What you need to know
-
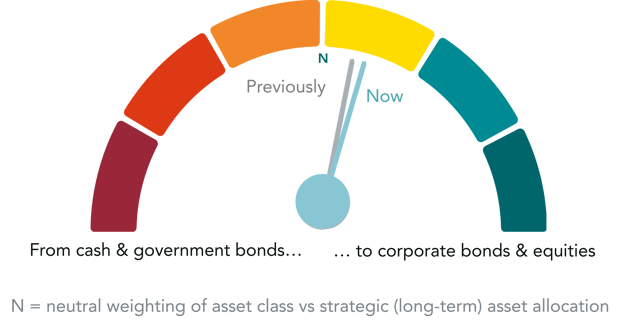
Falling bond prices caused by higher interest rates have reduced the share of bonds in our portfolios. As global growth and earnings have held up well despite geopolitical tensions, we’re comfortable keeping the slightly higher share of equities and are not rebalancing portfolios at this stage.
-
We are taking profits on US equal-weight equities and reallocating to the broader US market. Equal-weight equities have performed well, but we believe the case for further outperformance has weakened.
-
We remain moderately overweight equities, with a preference for the US and emerging markets. We remain cautious on US Treasuries and higher-risk credit markets. We also maintain overweight positions in gold and, to a lesser extent, European government bonds.
Source: In-house research. For other risk profiles and/or bespoke portfolios, please contact your client advisor.
Note: Any reference to portfolio positioning relates to our flagship core discretionary portfolios. Clients invested in other strategies, or in bespoke and advisory portfolios, should consult their Client Advisor.
Resilience amid geopolitical uncertainty
The conflict involving the US and Iran has kept geopolitical risks in focus over the summer. Energy markets have been particularly sensitive because of concerns about disruptions to oil shipments through the Strait of Hormuz.
Even so, the global economy is less vulnerable to oil shocks than in the past. Economies now use roughly 60% less energy to produce the same level of output than they did in the 1970s. This should help limit the economic impact of higher oil prices.
That said, energy prices could remain under pressure. Alternative shipping routes cannot fully replace disrupted flows through the Strait, which may keep inflation higher than central banks would like.
This creates a challenge for policymakers. Higher energy prices can weaken economic activity while simultaneously pushing inflation higher. We believe moderate interest rate increases are probable in the US, Europe and UK. However, rates are already higher than they were a few years ago, making a repeat of the aggressive tightening cycle that followed the 2022 energy shock less likely.
Debt sustainability moves to the forefront
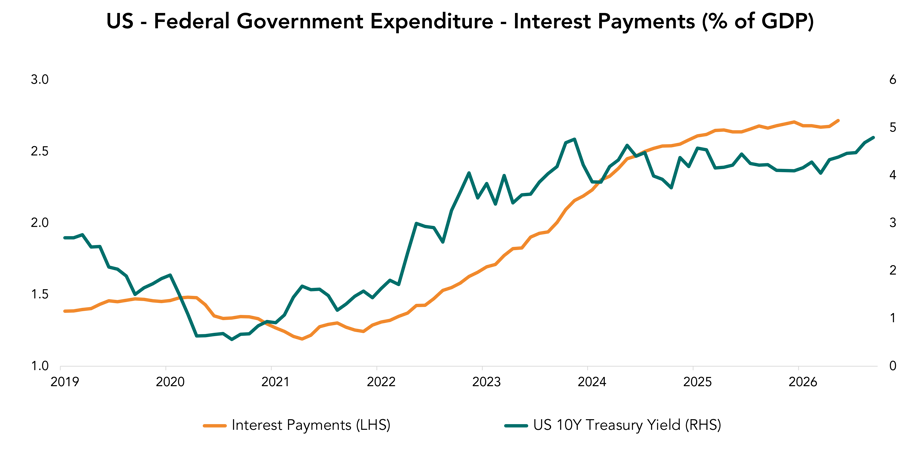
Government debt is becoming a more important issue for financial markets. In the US, public debt has risen to around USD 40 trillion. At the same time, higher energy costs and mortgage rates are adding to pressure on households. This makes the interaction between fiscal policy, inflation and interest rates particularly important for investors, especially at a time when long-term yields are already elevated.
Energy prices have risen lately, government borrowing is still high and geopolitical uncertainty hasn’t gone away. Treasury buybacks may support bond prices and could absorb roughly 15% of annual gross issuance of long-dated bonds, possibly limiting further increases in yields. However, they do not address the underlying fiscal dynamics, which is why we remain tactically underweight US Treasuries.
Currency markets may also feel the effects of higher yields. If bond prices fail to get support while fiscal concerns remain, that could weaken the US dollar. Gold provides another way to navigate this environment. Rising public debt, geopolitical uncertainty and continued central bank demand remain supportive structural factors. It can also help diversify portfolios when government bonds provide less protection against fiscal and geopolitical shocks than they have in the past. This is why we’re keeping our gold overweight.
Source: In-house research, LSEG Datastream. Past performance is not a reliable indicator of future returns.
Staying nimble as the market cycle evolves
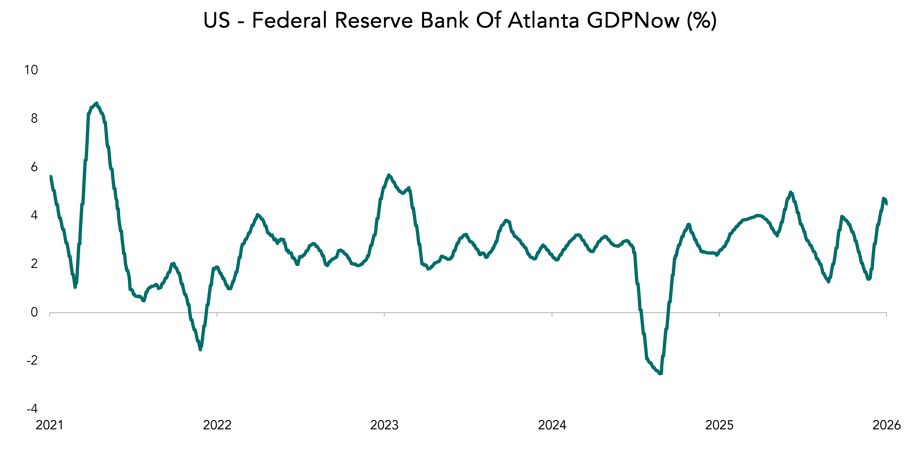
The investment backdrop is becoming more complicated, but the overall picture is reasonably healthy. The key question is whether these forces can continue to offset the pressures created by higher energy prices, tighter financial conditions and fiscal uncertainty. For now, we think they can.
Falling bond prices over the summer have led to a slightly higher share of equities within our portfolios. While this has led to a drift away from our target weights in portfolios, we are comfortable with these changes and are not actively rebalancing at this stage.
Given the balance of growth, earnings, inflation and policy risks, we believe our current portfolio allocation is appropriate. The global economy has entered this period from a position of reasonable strength, and the resilience of growth and earnings provides an important buffer against a more challenging policy environment.
Source: In-house research, LSEG Datastream; note: GDPNow is a real-time gauge of US economic growth; 21-day moving average, to facilitate visualisation.
Reshuffling within US equities
We are making one change within our US equity position. In 2024, we added an equal-weighted US equity position in portfolios. The aim was to reduce concentrated exposure to the largest US stocks and spread investments more evenly across the market.
As market breadth improved, the position performed well. We now believe the balance of risks and opportunities favours a normal market-cap-weighted index, so we’re switching our US equity position back to that.
There are three reasons for this change:
1. The US midterms
Prospects of a divided Congress, or even a Democratic sweep, reduce the likelihood of further fiscal stimulus and deregulation. These would have been beneficial for the industrial and financial sectors, which are both overrepresented in US equal-weight indices. Without those tailwinds, the case for further equal-weight outperformance is weaker.
2. Interest rate and economic sensitivity
Equal-weight equities tend to behave more like mid-cap stocks. These companies tend to have weaker balance sheets and are more sensitive to rising interest rates and tightening fiscal conditions than larger companies. If rates rise, that could become a headwind for the equal-weighted index.
3. Earnings and valuations
The broad US equity index continues to display stronger profitability than its equal-weighted counterpart. At the same time, valuations of large-cap US equities have improved relative to the equal-weighted index. In our view, this creates a better balance between earnings potential and valuation in the broader market.
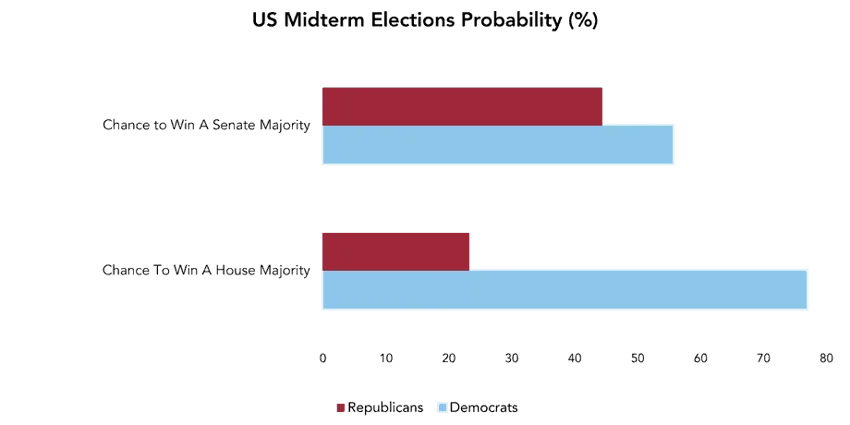
Source: In-house research, Race to the WH, Polymarket
What this means for portfolios
Even with this change, our long-term asset allocation remains well diversified across asset classes and regions. We maintain a lower allocation to US equities relative to their weight in global markets, helping mitigate concentration risks. The decision to move from equal-weight to market-cap-weighted US equities is therefore a tactical adjustment within a diversified portfolio, rather than a change in our overall approach to risk.
Successful investing is rarely about reacting to every headline. More often, it is about assessing how those developments change the outlook for growth, inflation, valuations and policy. When they do, it may be time to adapt portfolios. When they don’t, we believe staying disciplined is often the better approach.
The objective is not to predict when the next geopolitical shock will occur, when bond yields will peak or when the dollar will turn. Rather, it is to ensure that portfolios remain resilient across a range of plausible outcomes.
This document has been composed by InsingerGilissen, branch of Quintet Private Bank (Europe) S.A. (“InsingerGilissen”). InsingerGilissen is supervised by the ECB and CSSF and under limited supervision by the AFM and DNB. InsingerGilissen has its registered office at Herengracht 537, 1017 BV Amsterdam, The Netherlands (Chamber of Commerce-number: 80510132). Quintet Private Bank (Europe) S.A. has its statutory seat in Luxembourg.
This document is for information purposes only, does not constitute individual (investment or tax) advise and investment decisions must not be based merely on this document. Whenever this document mentions a product, service or advice, it should be considered only as an indication or summary and cannot be seen as complete or fully accurate. All (investment or tax) decisions based on this information are for your own expense and for your own risk. You should (have) assess(ed) whether the product or service is suitable for your situation. InsingerGilissen and its employees cannot be held liable for any loss or damage arising out of the use of (any part of) this document.
All copyrights and trademarks regarding this document are held by InsingerGilissen, unless expressly stated otherwise. You are not allowed to copy, duplicate in any form or redistribute or use in any way the contents of this document, completely or partially, without the prior explicit and written approval of InsingerGilissen. See the privacy notice on our website for how your personal data is used (https://www.insingergilissen.nl/en-gb/privacyencookies).